Biodun Iginla, BBC News

Biodun Iginla, BBC News
Showing posts with label financial news. Show all posts

Wednesday, February 27, 2019

BREAKING: Venezuela removed 8 tons of central bank gold last week

February 27, 2019  23H40  GMT/ZULU
CARACAS - At least 8 tons of gold were removed from the Venezuelan central bank’s vaults last week, an opposition legislator and three government sources told us at Reuters, in the latest sign of President Nicolas Maduro’s desperation to raise hard currency amid tightening sanctions.
FILE PHOTO: Venezuela's President Nicolas Maduro touches a gold bar as he speaks during a meeting with the ministers responsible for the economic sector at Miraflores Palace in Caracas, Venezuela March 22, 2018. REUTERS/Marco Bello/File Photo
The gold was removed in government vehicles between Wednesday and Friday last week when there were no regular security guards present at the bank, Legislator Angel Alvarado and the three government sources said.
“They plan to sell it abroad illegally,” Alvarado said in an interview.
ADVERTISEMENT
ADVERTISING
The central bank did not respond to requests for comment.
Alvarado and the government sources, who spoke on condition of anonymity, did not say where the central bank was sending the gold. They said the operation took place while central bank head Calixto Ortega was abroad on a trip.
In 2018, 23 tons of mined gold were transported from Venezuela to Istanbul by plane, according to sources and Turkish government data.
ADVERTISEMENT
The central bank bought part of this gold from primitive gold-mining camps in the south of Venezuela and exported it to Turkey and other countries to finance the purchase of basic food supplies, given widespread shortages, according to more than 30 people with knowledge of the trade.
Some 20 tons of monetary gold were also removed from the central bank’s vaults in 2018, according to the bank’s data, leaving 140 tonnes remaining, the lowest level in 75 years.
Abu Dhabi investment firm Noor Capital said on Feb. 1 that it bought 3 tons of gold on Jan. 21 from the Venezuelan central bank and would not buy more until Venezuela’s situation stabilized. Noor Capital said its purchase was in accordance with “international standards and laws in place” as of that date.
Maduro’s government has been seeking to repatriate some 31 tons of gold in the Bank of England’s vaults on fears it could be caught up in international sanctions on the country.
INSIGHT: Trump, Kim kick off second summit
Venezuelan Foreign Minister Jorge Arreaza said on Wednesday, during a United Nations meeting in Geneva, that the Bank of England had blocked the government’s assets.
Maduro’s government has resorted to selling off gold after falling oil production, the country’s wider economic collapse and mounting sanctions hit public income and made it hard for the country to access credit.
The United States, which is backing an attempt by opposition leader Juan Guaido to force Maduro to step down and call new elections, has warned bankers and traders not to deal in Venezuelan gold.

Thursday, February 8, 2018

Analysis: America’s extraordinary economic gamble

Souped up growth

by Judith Stein and Biodun Iginla, Financial News Analysts, The Economist Intelligence Unit, New York

Fiscal policy is adding to demand even as the economy is running hot
VOLATILITY is back. A long spell of calm, in which America’s stock market rose steadily without a big sell-off, ended abruptly this week. The catalyst was a report released on February 2nd showing that wage growth in America had accelerated. The S&P 500 fell by a bit that day, and by a lot on the next trading day. The Vix, an index that reflects how changeable investors expect equity markets to be, spiked from a sleepy 14 at the start of the month to an alarmed 37. In other parts of the world nerves frayed.
Markets later regained some of their composure (see article). But more adrenalin-fuelled sessions lie ahead. That is because a transition is under way in which buoyant global growth causes inflation to replace stagnation as investors’ biggest fear. And that long-awaited shift is being complicated by an extraordinary gamble in the world’s biggest economy. Thanks to the recently enacted tax cuts, America is adding a hefty fiscal boost to juice up an expansion that is already mature. Public borrowing is set to double to $1 trillion, or 5% of GDP, in the next fiscal year. What is more, the team that is steering this experiment, both in the White House and the Federal Reserve, is the most inexperienced in recent memory. Whether the outcome is boom or bust, it is going to be a wild ride.

Latest updates

See all updates
Fire your engines
The recent equity-market gyrations by themselves give little cause for concern. The world economy remains in fine fettle, buoyed by a synchronised acceleration in America, Europe and Asia. The violence of the repricing was because of newfangled vehicles that had been caught out betting on low volatility. However, even as they scrambled to react to its re-emergence, the collateral damage to other markets, such as corporate bonds and foreign exchange, was limited. Despite the plunge, American stock prices have fallen back only to where they were at the beginning of the year.
Yet this episode does signal just what may lie ahead. After years in which investors could rely on central banks for support, the safety net of extraordinarily loose monetary policy is slowly being dismantled. America’s Federal Reserve has raised interest rates five times already since late 2015 and is set to do so again next month. Ten-year Treasury-bond yields have risen from below 2.1% in September to 2.8%. Stock markets are in a tug-of-war between stronger profits, which warrant higher share prices, and higher bond yields, which depress the present value of those earnings and make eye-watering valuations harder to justify.
This tension is an inevitable part of the return of monetary policy to more normal conditions. What is not inevitable is the scale of America’s impending fiscal bet. Economists reckon that Mr Trump’s tax reform, which lowers bills for firms and wealthy Americans—and to a lesser extent for ordinary workers—will jolt consumption and investment to boost growth by around 0.3% this year. And Congress is about to boost government spending, if a budget deal announced this week holds up. Democrats are to get more funds for child care and other goodies; hawks in both parties have won more money for the defence budget. Mr Trump, meanwhile, still wants his border wall and an infrastructure plan. The mood of fiscal insouciance in Washington, DC, is troubling. Add the extra spending to rising pension and health-care costs, and America is set to run deficits above 5% of GDP for the foreseeable future. Excluding the deep recessions of the early 1980s and 2008, the United States is being more profligate than at any time since 1945.
A cocktail of expensive stockmarkets, a maturing business cycle and fiscal largesse would test the mettle of the most experienced policymakers. Instead, American fiscal policy is being run by people who have bought into the mantra that deficits don’t matter. And the central bank has a brand new boss, Jerome Powell, who, unlike his recent predecessors, has no formal expertise in monetary policy.
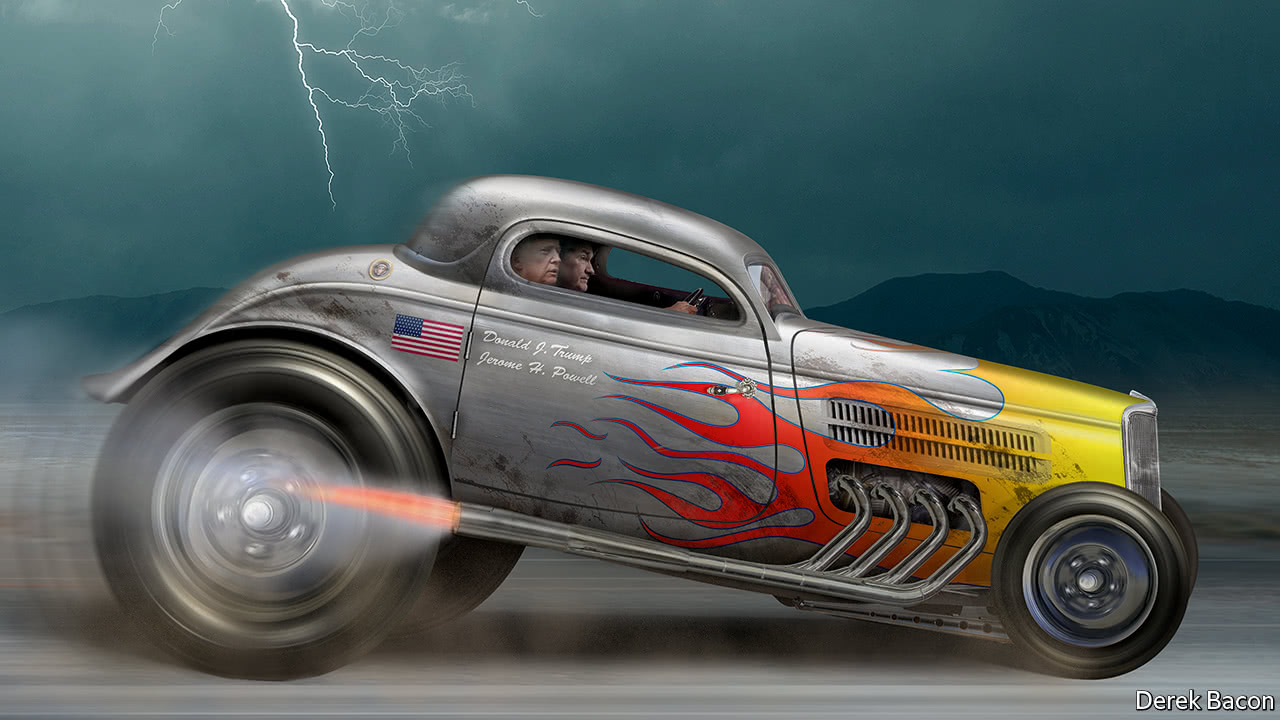
Does Powell like fast cars?
What will determine how this gamble turns out? In the medium term, America will have to get to grips with its fiscal deficit. Otherwise interest rates will eventually soar, much as they did in the 1980s. But in the short term most hangs on Mr Powell, who must steer between two opposite dangers. One is that he is too doveish, backing away from the gradual (and fairly modest) tightening in the Fed’s current plans as a salve to jittery financial markets. In effect, he would be creating a “Powell put” which would in time lead to financial bubbles. The other danger is that the Fed tightens too much too fast because it fears the economy is overheating.
On balance, hasty tightening is the greater risk. New to his role, Mr Powell may be tempted to establish his inflation-fighting chops—and his independence from the White House—by pushing for higher rates faster. That would be a mistake, for three reasons.
First, it is far from clear that the economy is at full employment. Policymakers tend to consider those who have dropped out of the jobs market as lost to the economy for good. Yet many have been returning to work, and plenty more may yet follow (see article). Second, the risk of a sudden burst of inflation is limited. Wage growth has picked up only gradually in America. There is little evidence of it in Germany and Japan, which also have low unemployment. The wage-bargaining arrangements behind the explosive wage-price spiral of the early 1970s are long gone. Third, there are sizeable benefits from letting the labour market tighten further. Wages are growing fastest at the bottom of the earnings scale. That not only helps the blue-collar workers who have been hit disproportionately hard by technological change and globalisation. It also prompts firms to invest more in capital equipment, giving a boost to productivity growth.
To be clear, we would not advise a fiscal stimulus of the scale that America is undertaking. It is poorly designed and recklessly large. It will add to financial-market volatility. But now that this experiment is under way, it is even more important that the Fed does not lose its head.

(This article appeared in the Leaders section of the print edition under the headline "Running hot")
Reuse this content

Thursday, November 23, 2017

Inheritance tax--analysis

by Judith Stein and Biodun Iginla, Financial News Analysts, The Economist Intelligence Unit, London/New York

A hated tax but a fair one

The case for taxing inherited assets is strong
NO TAX is popular. But one attracts particular venom. Inheritance tax is routinely seen as the least fair by Britons and Americans. This hostility spans income brackets. Indeed, surveys suggest that opposition to inheritance and estate taxes (one levied on heirs and the other on legacies) is even stronger among the poor than the rich.
Politicians know a vote-winner when they see one. The estate of a dead adult American is 95% less likely to face tax now than in the 1960s. And Republicans want to go all the way: the House of Representatives has passed a tax-reform plan that would completely abolish “death taxes” by 2025. For a time before the second world war, Britons were more likely to pay death duties than income tax; today less than 5% of estates catch the taxman’s eye. It is not just Anglo-Saxons. Revenue from these taxes in OECD countries, as a share of total government revenue, has fallen sharply since the 1960s (see article). Many other countries have gone down the same path. In 2004 even the egalitarian Swedes decided that their inheritance tax should be abolished.

Latest updates

See all updates
Yet this trend towards trifling or zero estate taxes ought to give pause. Such levies pit two vital liberal principles against each other. One is that governments should leave people to dispose of their wealth as they see fit. The other is that a permanent, hereditary elite makes a society unhealthy and unfair. How to choose between them?
When the heirs loom
Some people argue for a punitive inheritance tax. They start with the negative argument that dead people no longer enjoy the general freedom to disburse their wealth as they wish—as the dead have no rights. How could they, when they are not affected one way or the other by what happens in the world?
That does not ring true. The logic would be to abrogate even the most modest of wills. But inheritances are deeply personal and the biggest single gift that many give to causes they believe in and loved ones they may have cherished. Many (living) people would feel wronged if they could not provide for their children. If anything, as the expression of their last wishes, bequests carry more weight than their passing fancies do.
The positive argument for steep inheritance taxes is that they promote fairness and equality. Heirs have rarely done anything to deserve the money that comes their way. Liberals, from John Stuart Mill to Theodore Roosevelt, thought that needed correcting. Roosevelt, who warned that letting huge fortunes pass across generations was “of great and genuine detriment to the community at large”, would doubtless be aghast at the situation today. Annual flows of inheritance in France have tripled as a proportion of GDP since the 1950s. Half of Europe’s billionaires have inherited their wealth, and their number seems to be rising.
However, in 2017, it is not clear exactly how decisive a role inheritance plays in the entrenchment of the hereditary elite. Data from Britain suggest that people tend not to lose their parents before they reach the age of 50. In rich countries the advantages that wealthy parents pass to their offspring begin with the sorting mechanism of marriage, in which elites increasingly pair up with elites (see article). They continue with the benefits of education, social capital and lavish gifts, not in the deeds to the ancestral pile.
Even if the link between inheritance-tax rates and inequality were clear, wealth can pay for a good tax lawyer. In the century since Roosevelt, Sweden and other high-taxers discovered that if governments impose a steep enough duty, the rich will find ways to avoid it. The trusts they create as a result can last even longer than the three generations it takes for family fortunes to go from clogs to clogs.
Armed with such arguments, some leap to the other extreme, proposing, as the American tax reform does, that there should be no inheritance tax at all. Not only is it right to let people hand their private property to their children, they say, but also bequests are often the fruits of labour that has already been taxed. And a large inheritance-tax bill is destructive, because it can cause the dismemberment of family firms and farms, and force the sale of ancestral homes.
Yet every tax is an intrusion by the state. If avoiding double taxation were a requirement of good policy, then governments would need to abolish sales taxes, which are paid out of taxed income. The risks that heirs will be forced to sell homes and firms can be mitigated by allowing them to pay the duties gradually, from cashflow rather than by fire-sales.
In fact, people who are against tax in general ought to be less hostile to inheritance taxes than other sorts. However disliked they are, they are some of the least distorting. Unlike income taxes, they do not destroy the incentive to work—whereas research suggests that a single person who inherits an amount above $150,000 is four times more likely to leave the labour force than one who inherits less than $25,000. Unlike capital-gains taxes, heavier estate taxes do not seem to dissuade saving or investment. Unlike sales taxes, they are progressive. To the extent that a higher inheritance tax can fund cuts to all other taxes, the system can be more efficient.
Transfer market
The right approach is to strike a balance between the two extremes. The precise rate will vary from country to country. But three design principles stand out. First, target the wealthy; that means taxing inheritors rather than estates and setting a meaningful exemption threshold. Second, keep it simple. Close loopholes for those who are caught in the net by setting a flat rate and by giving people a lifetime allowance for bequests; set the rate high enough to raise significant sums, but not so high that it attracts massive avoidance. Third, with the fiscal headroom generated by higher inheritance tax, reduce other taxes, lightening the load for most people.
A sensible discussion is hard when inheritance taxes prompt such a visceral reaction. But their erosion has attracted too little debate. A fair and efficient tax system would seek to include inheritance taxes, not eliminate them.
This article appeared in the Leaders section of the print edition under the headline "The case for taxing death"

Friday, November 17, 2017

Wall Street: Analysts flee with gallows humor as research changes loom

NOVEMBER 17, 2017  12H:43 GMT/UTC/ZULU TIME
Having covered financial stocks at big and small banks for more than two decades, David Hilder was accustomed to the ebb and flow of Wall Street job cuts and hiring sprees.
A souvenir license plate is seen outside the New York Stock Exchange in Manhattan, New York City, U.S., December 21, 2016. REUTERS/Andrew Kelly
But he threw in the towel as an analyst last year after deciding customers simply will not pay what it costs to produce research in the years ahead, especially after a regulation called MiFID II upended the pricing model.
SPONSORED
“It certainly seemed that the difficulty of being paid for research was going to increase, not decrease,” said Hilder, who is now trying to reinvent himself as an investment banker.
Many share Hilder’s grim outlook. Reuters spoke to dozens of current and former analysts who moved to independent research shops or investment firms, joined companies in industries they covered, or have launched new careers or are considering doing so, after nearly a decade of cost-cutting that is likely to accelerate under MiFID.
Major global investment banks have slashed their equity research budgets by more than half, from a peak of $8.2 billion in 2008 to $3.4 billion in 2017, according to Frost Consulting. The top 10 banks are expected to cut those budgets by another 30 percent in the near term, due largely to MiFID, McKinsey projects.
The rule handed down by European regulators, aimed at boosting transparency on costs, is changing the way brokerages can charge for research.
Instead of offering free reports and advice in exchange for some minimum amount of trading business, as they do now, brokerages will have to charge separately for research products and services. Although U.S. regulators are not immediately forcing firms here to comply, many banks are implementing changes globally.
Pricing models rolled out recently by Morgan Stanley (MS.N) and JPMorgan Chase & Co (JPM.N) charge thousands of dollars an hour for meetings or phone calls, and tens or even hundreds of thousands of dollars a year for basic research.
The change has put renewed pressure on senior analysts, who typically earn anywhere from $500,000 to $2 million a year, to prove their worth.
The heads of research at two Wall Street banks told us at Reuters that they measure productivity by logging analysts’ phone calls, emails and meetings, then gauge how much customers actually value their advice with methods like tracking how many messages they open.
That helps bosses decide who should be cut and who the real stars are, industry sources said. Management teams worry that top analysts and young up-and-comers they want to keep will follow colleagues out the door.
“In some areas you are seeing money being thrown at talented analysts ... to make sure they stay through the MiFID implementation period,” said Erick Davis, chief executive officer of Autonomous Research, a boutique shop not attached to a brokerage.
But ultimately, he said, “the asset management world doesn’t need 30 analysts covering a stock.”

PHONE CALL HAGGLING

The dynamic has created a morbid atmosphere in research divisions, where analysts said it feels like the “Sword of Damocles” is hanging over their heads.
On earnings calls in October, analysts asked bank chief executives how the research model would change, effectively checking in on their own jobs.
Evercore ISI analyst Glenn Schorr recently titled a research note “Writing My Obituary,” with a follow-up called “Stay of (my) Execution.”
“For the last few years, it’s been all about morgue humor like ‘flat is the new up’ and ‘no bonus, but at least you get to keep your job,'” said one former analyst who recently left a large bank but would not be quoted by name to avoid upsetting former or future employers.
“Contrast that with Silicon Valley,” he continued. “It’s not even the money; it’s the optimism that I envy. Those guys are building a brighter future and this just feels like death.”
Some have decided to launch career makeovers.
Sean McGowan spent 25 years covering consumer stocks at small and mid-size brokers before losing his job early last year amid broad cost-cutting.
After considering analyst roles at other banks, he took a job at an investor relations firm.
“The more I started to do research on the impact of MiFID and what was likely to happen to the industry, the more I realized that going back to that world would be like swimming upstream,” said McGowan. “A lot of the jobs on the sell-side are going to disappear and inevitably some of the more enjoyable parts will be peeled back. I don’t want to haggle someone about the price of a phone call.”