Biodun Iginla, BBC News

Biodun Iginla, BBC News
Showing posts with label Jerome Powell. Show all posts

Wednesday, November 13, 2019

ANALYSIS: America’s yield curve


by Judith Stein and Biodun Iginla, The Economist Intelligence Unit News Analysts


Inverse psychology
America’s yield curve is no longer inverted

So, no need to worry about recession? Hmm, maybe
United States


WHAT DO YOU get when you subtract the yield on short-term government bonds from that on longer-dated ones? A powerful economic omen, if recent history is any indicator. Around a year before each of the past three recessions the yield curve—which shows the return on government bonds from very short durations to very long ones—inverted. In July 2000, for instance, the yield on ten-year Treasury bonds dropped below that on three-month Treasury bills; by March 2001 the American economy had sunk into recession (see chart). When the same thing happened in March this year, alarm bells rang across corporate boardrooms and political campaigns. When the inversion deepened over the summer, traders and pundits began to speak of recession as a real possibility.
Now, however, the curve has righted itself. From mid-October, long-term bond yields rose back above short ones (a move accompanied by other bullish financial-market signs, like rising stocks). Market-watchers are asking: was that a false alarm?
Few economists think a yield curve inversion itself causes a slowdown. The link between the two has more to do with the effect of monetary policy on both. Short-term bond yields go up when the Federal Reserve raises its policy rate to keep the economy from overheating. A drop in long-term yields often occurs when markets expect slower growth ahead: a sign that the Fed has tightened a step or two too many, hitting the brakes hard enough to drag the economy into recession.
This time around, the Fed seemed to take the omen seriously. Over the course of 2019 it has first abandoned plans to keep raising rates (which had been going up since 2015), then cut its policy rate three times, reducing the effective rate from 2.4% or so to 1.55%. The yield curve was not the only thing on the mind of its chairman, Jerome Powell: cuts were also a response to a deepening slump in manufacturing and a plateau in the growth rates of prices and wages. But the central bank nonetheless responded faster and more fiercely to an inversion than it usually had. If rate reductions have in fact spared the American economy from recession, then Mr Powell, by reacting promptly to the yield-curve omen, may have actually weakened its predictive power. Few workers, or presidents, are likely to complain.
But the coast is not yet clear. The Fed might yet seize defeat from the jaws of victory. Rather than recognising its own success, it could interpret the un-inversion of the yield curve, and the absence (so far) of a downturn, as a sign that the original omen was a false alarm. Were a new round of headwinds to threaten the American economy and re-invert the curve, the central bank might wrongly dismiss the signal and under-respond, thus bringing on the foretold recession.
It could also be that the slump that was predicted still looms ahead. Less than a year has gone by since the yield curve first inverted. Perhaps more important, each of the past three pre-recession inversions reversed themselves before the ensuing downturn began. So while financial markets are celebrating a bullet dodged, the bullet may still be on its way.
Reuse this contentThe Trust Project

Wednesday, October 30, 2019

ANALYSIS: America’s economy

by Judith Stein and Biodun Iginla, The Economist Intelligence Unit Business News Analysts


Easy now
America’s economy is resisting the pull of recession

A healthy jobs market keeps Americans spending, helping to make up for a shortfall in business investment
United States


THIS WAS not the way it was supposed to go. “Four, five, and maybe even six percent” growth was what President Donald Trump promised in December 2017. Even within the relatively sober pages of the budget proposal released by the administration in March this year, Mr Trump’s team forecast economic growth rates of 3% or more right through 2024—which would be the last full year of a second Trump term, were one to occur. Instead, the American economy, which just missed the 3% growth target in 2018 despite the boost from the president’s budget-busting tax bill, continues to lose steam. In the third quarter of this year GDP, adjusted for inflation, rose at an annualised rate of 1.9%, down from 2% in the previous three months. The question hanging over Mr Trump, and millions of American workers, is just how far the slowdown will run and how deep it will go.
The first signs of trouble for America’s economy appeared in late 2018. Housing construction slumped as higher mortgage rates (pushed upward by Federal-Reserve interest-rate hikes) combined with rising home prices to drive buyers from the market. At the same time, a global slowdown in manufacturing and trade weighed on American producers. New manufacturing orders dropped fairly steadily from September of 2018 until May of this year, and parts of America’s manufacturing heartland experienced declines in factory employment. Economy-watchers have waited anxiously in the months since to see whether weakness in industry and construction would bleed into the service sector, where most Americans work.
Mounting anxiety eventually roused the Fed to action. The central bank spent most of 2018 raising its benchmark interest rates in order to keep inflation in check, despite some withering criticism emanating from the president’s Twitter account. As the world economy sputtered, the Fed slowly changed course: first halting its cycle of increasing rates, then cutting them by 0.25% in both July and September of this year. Jerome Powell, the Fed’s chairman, insisted that the moves represented a “mid-cycle adjustment”, lest markets interpret the cuts as a sign that the end of the boom—America’s longest on record—was nigh.
The cuts appear to have helped. Mortgage rates have retreated; the average rate on 30-year loans, which rose to near 5% a year ago, has dropped back to 3.75%. That has put a bit of wind back in the sails of the residential construction industry, which began work on about 20,000 more homes in September of this year than in the same month last year. Residential investment contributed positively to GDP growth in the third quarter, the first time it had done so in nearly two years. Rate cuts also seem to have switched off the bright, blinking recession-warning light which is the “yield curve”. “Inversions” of the yield curve, which occur when rates on long-term government bonds fall below those on short-term government debt, frequently appear a year or so before the onset of recession. The curve inverted over the summer, fuelling recession worries, but has since flipped back. Stock prices, which looked sickly in May, have roared back to touch record highs, buoyed by better than expected earnings reports, as well as the prospect of a trade truce between America and China.
On October 30th the Fed reduced its benchmark rate once more, by another 0.25%. But in doing so it very nearly declared victory in the battle to ward off a downturn. Markets now expect the Fed to hold its ground for at least the next six months. Mr Powell, while emphasising that the Fed will be watching the data closely, said, “We see the current stance of monetary policy as likely to remain appropriate...We believe monetary policy is in a good place.” A majority of members of the rate-setting committee reckon the Fed should resume rate increases in 2020.
The Fed’s confidence, while understandable, may be premature. The conditions which weighed on the economy earlier in the year have eased a little, but the growth scare did its damage. Consumers have been the motor driving the economy forward through its headwinds. They continue to spend, but their faith seems to have been shaken. Personal consumption spending grew at a 2.9% annual pace in the third quarter: not bad, but down from a blistering 4.6% pace in the second. Retail sales in September dropped by 0.3%, suggesting that the quarter ended on a particularly weak note. Measures of consumer confidence—a guide to how spending may evolve in future—have also slipped.
Firms, too, are behaving cautiously. Measures of business confidence have been softening. Anxiety among bosses is affecting investment: the boost to third-quarter GDP from investment in housing was more than offset by a hefty drop in investment in non-residential building and equipment. Weak investment figures are particularly irksome to economists in the Trump administration, who argued that the president’s tax reform would encourage a boom in business spending. Business enthusiasm could recover a bit in the months to come, if indeed a trade-war ceasefire is declared. But the trade war is only partly responsible for firms’ woes. More important is the worldwide slowdown. Both Europe and Japan have slipped close to the brink of recession, and the deceleration in Chinese growth shows few signs of abating. A turnaround in American economic fortunes, if it occurs, will begin with homegrown optimism.
Hopes for that hinge in turn on the health of the labour market. The jobs picture has been the most enduring source of encouragement to those looking on the bright side. The pace of hiring has slowed; payrolls have risen by 1.4% over the past 12 months, down from 1.8% over the year before that. But that is not an unexpected development this deep into an economic expansion, when fewer jobless workers remain to be hired. The unemployment rate, at 3.5%, remains extraordinarily low. So long as firms continue to hire and wages to grow, consumers are likely to keep spending at rates sufficient to steer the economy clear of a downturn.
Given the uncertainty surrounding the path of the economy, the Fed might have been expected to signal its readiness to keep cutting rates, if necessary, more clearly. Confidence is easier to maintain than to restore, and the risks of a surge in inflation have fallen in recent months. The price index for personal consumption expenditures, the Fed’s preferred inflation measure, rose at a 1.5% annual pace in the third quarter: below the Fed’s 2% target and down from 2.4% in the second. Instead, the central bank seems content to wait and see how conditions develop—and to allow a president facing threats from all sides to twist in the wind.
Reuse this contentThe Trust Project

Friday, February 22, 2019

ANALYSIS: Trade tensions, Brexit poses risk to US economy: Fed


The prospects that Britain will leave the European Union without an agreement could create "wide a range of economic and financial activities" that could be disrupted, despite the Federal Reserve's preparations
The prospects that Britain will leave the European Union without an agreement could create "wide a range of economic and financial activities" that could be disrupted, despite the Federal Reserve's preparations AFP/File
ADVERTISING
Washington 
Continued trade tensions and Brexit are key risks facing the US economy and could undermine financial stability, the Federal Reserve cautioned Friday.
"Potential downside risks to international financial stability include a downturn in global growth, political and policy uncertainty, an intensification of trade tensions and broadening stress in emerging market economies," the Fed said in its semi-annual report on monetary policy.
ADVERTISING
Those concerns caused the Fed to shift to wait-and-see mode after raising interest rates four times in 2018, after "volatility in financial markets and increased concerns about global growth made the appropriate extent and timing of future rate increases more uncertain than earlier."
And the prospects that Britain will leave the European Union without an agreement could create "a wide range of economic and financial activities could be disrupted," despite preparations.
"Without such a withdrawal agreement, there will be no transition period for important trade and financial interactions between UK and EU residents."
The report was prepared for Congress to accompany the twice-yearly testimony by Fed Chairman Jerome Powell, who will appear Tuesday and Wednesday to answer questions about monetary policy.
Powell and other central bankers late last year pivoted sharply away from expectations that more increases in the lynchpin for borrowing costs would be needed this year.
Instead, they clearly and repeatedly signaled they will pause for now.
The report cited tariffs as a key risk to rising inflation but falling oil prices and a strong dollar could dampen inflation.
In fact the trade tensions with China -- which are subject to high-stakes negotiations this week -- are mentioned more than 20 times in the nearly 60-page report.
The report repeated that the Fed continued to expect the US economy to put in a solid performance this year, with inflation approaching the two percent target.

Thursday, February 8, 2018

Analysis: America’s extraordinary economic gamble

Souped up growth

by Judith Stein and Biodun Iginla, Financial News Analysts, The Economist Intelligence Unit, New York

Fiscal policy is adding to demand even as the economy is running hot
VOLATILITY is back. A long spell of calm, in which America’s stock market rose steadily without a big sell-off, ended abruptly this week. The catalyst was a report released on February 2nd showing that wage growth in America had accelerated. The S&P 500 fell by a bit that day, and by a lot on the next trading day. The Vix, an index that reflects how changeable investors expect equity markets to be, spiked from a sleepy 14 at the start of the month to an alarmed 37. In other parts of the world nerves frayed.
Markets later regained some of their composure (see article). But more adrenalin-fuelled sessions lie ahead. That is because a transition is under way in which buoyant global growth causes inflation to replace stagnation as investors’ biggest fear. And that long-awaited shift is being complicated by an extraordinary gamble in the world’s biggest economy. Thanks to the recently enacted tax cuts, America is adding a hefty fiscal boost to juice up an expansion that is already mature. Public borrowing is set to double to $1 trillion, or 5% of GDP, in the next fiscal year. What is more, the team that is steering this experiment, both in the White House and the Federal Reserve, is the most inexperienced in recent memory. Whether the outcome is boom or bust, it is going to be a wild ride.

Latest updates

See all updates
Fire your engines
The recent equity-market gyrations by themselves give little cause for concern. The world economy remains in fine fettle, buoyed by a synchronised acceleration in America, Europe and Asia. The violence of the repricing was because of newfangled vehicles that had been caught out betting on low volatility. However, even as they scrambled to react to its re-emergence, the collateral damage to other markets, such as corporate bonds and foreign exchange, was limited. Despite the plunge, American stock prices have fallen back only to where they were at the beginning of the year.
Yet this episode does signal just what may lie ahead. After years in which investors could rely on central banks for support, the safety net of extraordinarily loose monetary policy is slowly being dismantled. America’s Federal Reserve has raised interest rates five times already since late 2015 and is set to do so again next month. Ten-year Treasury-bond yields have risen from below 2.1% in September to 2.8%. Stock markets are in a tug-of-war between stronger profits, which warrant higher share prices, and higher bond yields, which depress the present value of those earnings and make eye-watering valuations harder to justify.
This tension is an inevitable part of the return of monetary policy to more normal conditions. What is not inevitable is the scale of America’s impending fiscal bet. Economists reckon that Mr Trump’s tax reform, which lowers bills for firms and wealthy Americans—and to a lesser extent for ordinary workers—will jolt consumption and investment to boost growth by around 0.3% this year. And Congress is about to boost government spending, if a budget deal announced this week holds up. Democrats are to get more funds for child care and other goodies; hawks in both parties have won more money for the defence budget. Mr Trump, meanwhile, still wants his border wall and an infrastructure plan. The mood of fiscal insouciance in Washington, DC, is troubling. Add the extra spending to rising pension and health-care costs, and America is set to run deficits above 5% of GDP for the foreseeable future. Excluding the deep recessions of the early 1980s and 2008, the United States is being more profligate than at any time since 1945.
A cocktail of expensive stockmarkets, a maturing business cycle and fiscal largesse would test the mettle of the most experienced policymakers. Instead, American fiscal policy is being run by people who have bought into the mantra that deficits don’t matter. And the central bank has a brand new boss, Jerome Powell, who, unlike his recent predecessors, has no formal expertise in monetary policy.
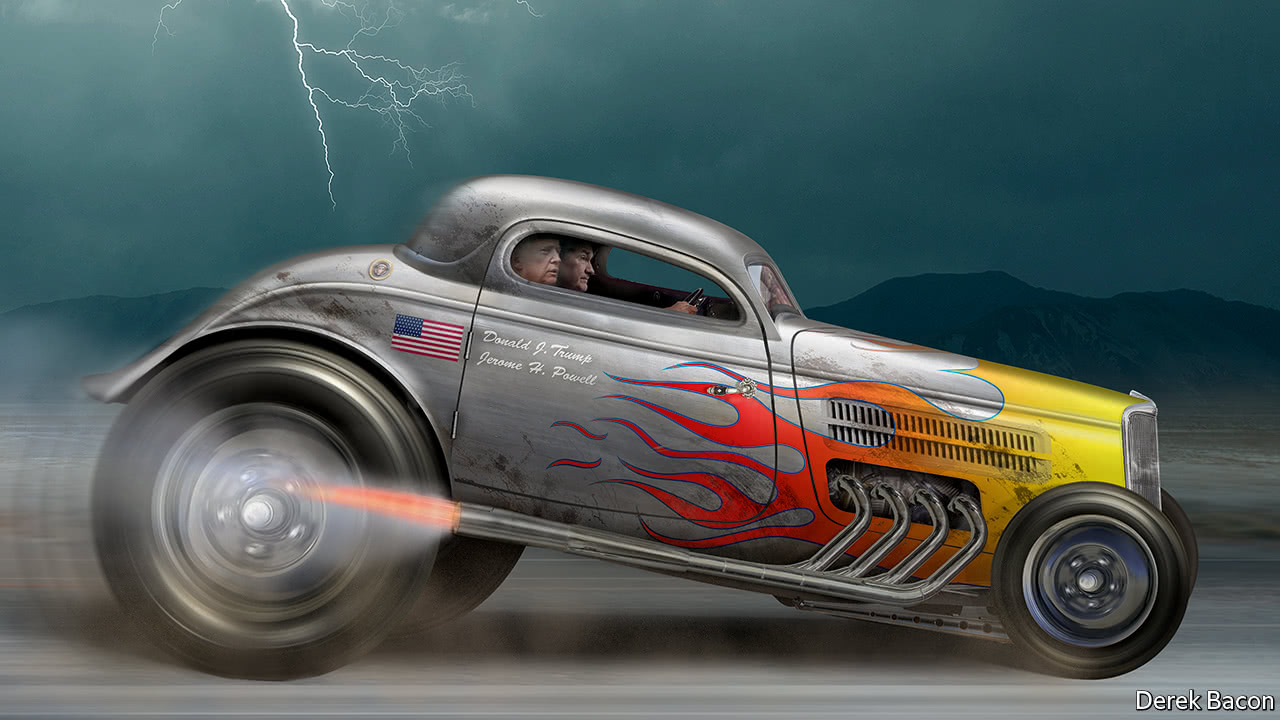
Does Powell like fast cars?
What will determine how this gamble turns out? In the medium term, America will have to get to grips with its fiscal deficit. Otherwise interest rates will eventually soar, much as they did in the 1980s. But in the short term most hangs on Mr Powell, who must steer between two opposite dangers. One is that he is too doveish, backing away from the gradual (and fairly modest) tightening in the Fed’s current plans as a salve to jittery financial markets. In effect, he would be creating a “Powell put” which would in time lead to financial bubbles. The other danger is that the Fed tightens too much too fast because it fears the economy is overheating.
On balance, hasty tightening is the greater risk. New to his role, Mr Powell may be tempted to establish his inflation-fighting chops—and his independence from the White House—by pushing for higher rates faster. That would be a mistake, for three reasons.
First, it is far from clear that the economy is at full employment. Policymakers tend to consider those who have dropped out of the jobs market as lost to the economy for good. Yet many have been returning to work, and plenty more may yet follow (see article). Second, the risk of a sudden burst of inflation is limited. Wage growth has picked up only gradually in America. There is little evidence of it in Germany and Japan, which also have low unemployment. The wage-bargaining arrangements behind the explosive wage-price spiral of the early 1970s are long gone. Third, there are sizeable benefits from letting the labour market tighten further. Wages are growing fastest at the bottom of the earnings scale. That not only helps the blue-collar workers who have been hit disproportionately hard by technological change and globalisation. It also prompts firms to invest more in capital equipment, giving a boost to productivity growth.
To be clear, we would not advise a fiscal stimulus of the scale that America is undertaking. It is poorly designed and recklessly large. It will add to financial-market volatility. But now that this experiment is under way, it is even more important that the Fed does not lose its head.

(This article appeared in the Leaders section of the print edition under the headline "Running hot")
Reuse this content